Summary: FIGS game localization (French, Italian, German, and Spanish) opens access to a combined addressable reach approaching half a billion gamers and $15+ billion in game software and in-game revenue across the core markets in Europe and Latin America. Despite the rise of Chinese, Arabic, and Korean as priority languages, FIGS translation remains one of the highest-ROI starting point for most studios releasing in English.
FIGS has been the default European localization bundle for so long that some teams pick it on autopilot. That used to be fine. In 2026, it isn’t.
Localization budgets are tighter, the language map has shifted (Chinese, Arabic, and Brazilian Portuguese all have stronger cases than they did five years ago), and within FIGS itself the gap between the strongest and weakest market has widened. So before you sign off on “let’s just do FIGS,” it’s worth knowing exactly what you’re buying.
To do so, we’ll adress the following:
- What does FIGS game localization actually mean, and how is it different from EFIGS?
- Is it still worth it in 2026, or has the calculus shifted?
- How do the four markets compare on players, revenue, and spend?
- What challenges should you budget for that you probably aren’t thinking about?
- Which FIGS language should you ship first if you can’t ship all four?
What is FIGS in game localization?
FIGS stands for French, Italian, German, and Spanish, the four major Western European languages that, together with English, form the standard launch bundle for most non-Asian game releases. You’ll also see EFIGS (with English) and EFIGS+ (with Brazilian Portuguese, sometimes Russian) used by larger studios.
The grouping isn’t arbitrary. These four languages share a few traits that make them economical to tackle as a batch:
- They reach the four largest gaming markets in the EU plus a long tail of secondary markets (Latin America for Spanish, Quebec and Africa for French, Switzerland and Austria for German).
- They have mature gaming cultures with established expectations for fully localized text and, increasingly, voice-over.
- They share localization gotchas (text expansion, gendered grammar, formality decisions) that a translation team can systematize once and apply across all four.
What FIGS is not is a single market. Treating it as one is the most common mistake we see. Germany behaves nothing like Mexico. France behaves nothing like Argentina. The grouping is a procurement convenience, not a strategic reality.
Is FIGS game localization still worth it in 2026?
Yes. Without question. For almost every studio releasing in English. That’s not to say there aren’t details to consider.
Here’s the big picture. Across the four languages, you’re looking at:
- A combined addressable reach approaching half a billion gamers worldwide who speak one of the four as a native or competent second language (with meaningful bilingual overlap in Europe, a Belgian gamer may speak French, German, and Dutch).
- $15+ billion in combined annual game software and in-game revenue across the core markets (Germany, France, Italy, Spain, Mexico, plus a long tail).
- Per-user spend in the top FIGS markets that consistently sits above the global average, with Italy and Germany among the highest-ARPU markets in the world.
Nothing else gives you that much addressable market for a single procurement decision. Even if you only ship two of the four, the math usually works.
The harder question is which two, and that’s where the comparison below matters.
The four FIGS markets at a glance
This is the table to bookmark. All figures are 2024–2025 data from Newzoo, AEVI, IIDEA, the German Games Industry Association, and Instituto Cervantes. The “core market” is the country we recommend leading with for each language.
| Language | Total speakers (worldwide) | Total gamers (worldwide) | Core market | Core market revenue | Core market players | Notable |
|---|---|---|---|---|---|---|
| French | ~327M | ~120M | France | $4B+ annually; $8.3B projected by 2027 | 40M+ | Fastest-growing speaker base globally (Africa) |
| Italian | ~66M | ~30M | Italy | $3.6B (2022), $6.4B projected by 2025 | ~25.8M | Among highest ARPU globally (~$960) |
| German | ~154M | ~87.5M | Germany | $5B in games + IAP; ~$11B total industry | 45M active | $113 per-gamer spend, ~2× global average |
| Spanish | ~636M | ~285M | Mexico (volume) / Spain (value) | Mexico $2.7B / Spain €2.41B | Mexico 78.1M / Spain 22.1M | Largest reach; most market fragmentation |
A few things jump out:
- Spanish wins on reach by a wide margin. It’s not close. If your KPI is total addressable players, Spanish is the first FIGS language to ship.
- German wins on monetization. Germany is Europe’s largest gaming market by overall revenue, and German gamers spend an average of $113 per year on game software and in-game purchases, nearly double the global average.
- Italian wins on engagement. The market is smaller, but the players spend like crazy and stick around. Loyalty and ARPU make it punch above its weight.
- French is the geographic bet. France is solid today, but the long-term thesis is the African francophone population doubling by 2050. If your game has a long live-service tail, French gets more valuable every year.
Note: Market data varies meaningfully across sources (especially for Germany). Newzoo, AEVI, IIDEA, the German Games Industry Association, and Instituto Cervantes each use different definitions of “gamer,” different revenue cuts (some include hardware, some don’t; some include subscriptions, some don’t), and different reporting periods. The figures in this article reflect the most recent publicly available data from each source as of 2024–2025, and we’ve flagged the methodology behind major claims.
French game localization
- Players reached: Roughly 120 million French-speaking gamers globally.
- Primary market: France.
- Best for: Live-service titles, RPGs, broad-audience console/PC releases.
French is the original FIGS language and still the most reliable revenue line for most studios. France consistently ranks among the top global gaming markets (typically seventh to tenth depending on source and year) with over 40 million players and roughly $4 billion in annual revenue, projected to reach $8.3 billion by 2027.
Beyond France, the language opens up Belgium, Switzerland, Luxembourg, Quebec (where 8.8 million native speakers live), and a rapidly growing African base. The Organisation internationale de la Francophonie projects the global French-speaking population will hit 700 million by 2050, with 90% of the world’s youth coming from francophone Africa.
That growth doesn’t translate to revenue today (purchasing power in Sub-Saharan Africa remains limited and piracy is high) but it shifts the long-term value calculation.
For 99% of projects, you should base French localization on standard European French from France. Quebec French diverges enough that Canadian players notice, but the cost of maintaining a separate Quebec variant only pays off if you have evidence of strong traction in that market specifically.
A few practical notes:
- French is roughly 15–20% longer than English. Budget UI rework.
- The AZERTY keyboard layout requires you to remap control schemes for PC releases.
- French gamers are particularly sensitive to translation quality. Half-baked machine translation gets called out hard in reviews.
Read the full French game localization breakdown for per-region data, gamer profiles, and revenue by territory.
Italian game localization
- Players reached: Roughky 30 million Italian-speaking gamers globally.
- Primary market: Italy.
- Best for: RPGs, mid-core console games, premium titles with strong narrative.
Italian looks like the smallest FIGS opportunity on paper, it has by far the smallest global speaker base of the four (66 million vs. Spanish’s 636 million), and that’s exactly why it’s underrated. The metric that matters here isn’t reach, it’s ARPU.
Italian gamers spend around $959 per year on average (per IIDEA), one of the highest figures globally. The Italian gaming market was worth $3.6 billion in 2022 and is projected to hit $6.4 billion in 2025, growing at a 6.56% CAGR through 2029. Players average 17.5 monthly play sessions and 4.1 sessions per week. They’re loyal, engaged, and they pay.
The catch is that English proficiency in Italy is genuinely low compared to other Western European countries, which means shipping without Italian localization in this market is more punishing than the equivalent decision in Germany or Spain. Italian players expect their language and tend to skip games that don’t deliver it.
One localization decision matters more in Italian than in the other FIGS: formality. Italian distinguishes between “tu” (informal) and “Lei” (formal), and the choice signals genre. RPGs in medieval or fantasy settings often default to “Lei”; competitive shooters and casual mobile games go “tu”. Pick deliberately and apply consistently.
Read the full Italian game localization breakdown for ARPU data, gamer demographics, and platform-specific revenue splits.
German game localization
- Players reached: Roughly 87.5 million German-speaking gamers globally.
- Primary market: Germany.
- Best for: High-budget releases, console, premium PC, anything that needs voice-over.
If you can only afford to localize into one FIGS language, German is the safest bet. It combines Europe’s largest absolute gaming market with strong per-gamer software spend. Germany alone has 45 million active gamers who spend money, with a per-gamer spend of $113 (nearly double the global average) and a total industry value approaching $11 billion. The market grew 6% in 2023 and shows no signs of slowing.
The German gamer profile is also unusually attractive: an even gender split (slightly female-majority at 52%), an average age of 38, and strong cross-platform behavior. These are mature, loyal players with established spending habits.
But German is also the most technically demanding FIGS language to localize well:
- Text expansion is brutal. German strings run 10–35% longer than English, and compound words (*Charaktererstellungsmenü* for “character creation menu”) will break UI you thought was safe.
- The QWERTZ keyboard swaps Y and Z, moves brackets, and changes how Strg (Ctrl) and AltGr work. Control schemes need remapping.
- § 86a StGB prohibits the display of unconstitutional symbols (Nazi imagery, SS runes, certain flags and gestures). Games depicting WWII or fascist regimes require a separate German build with assets swapped out. Wolfenstein renamed Hitler to “Heiler” and removed his mustache. Hearts of Iron greys out portraits and replaces flags. If your game touches this historical period, plan for a parallel asset pipeline from day one.
The upside is that German players reward serious effort. The downside is they punish lazy localization more visibly than any other FIGS market, the Terraria “Karte für Behinderte” mistranslation is the case study every German loc team studies.
Read the full German game localization breakdown for revenue by platform, regulatory deep dive, and quality control recommendations.
Spanish game localization
- Players reached: Roughly 285 million Spanish-speaking gamers globally.
- Primary market: Mexico (volume) / Spain (value).
- Best for: Mobile, free-to-play, broad-reach titles, anything scaling to LATAM.
Spanish is the FIGS language with by far the largest reach, roughly 636 million potential speakers worldwide and an estimated 285 million Spanish-speaking gamers. But it’s also the most fragmented, and that’s the trap.
There is no single “Spanish market.” There are two anchor markets (Mexico and Spain), a strong second tier (Argentina, Colombia), a meaningful third tier (Chile, Peru), and a long tail of Central and South American markets. Their player profiles diverge significantly:
- Spain is a mature, multi-platform, gender-balanced market with 22.1 million players and €2.41 billion in revenue (AEVI 2024). Broad age distribution, high weekly engagement.
- Mexico is mobile-first and younger. 78.1 million players (Newzoo 2025), $2.7 billion in revenue, 85% of gamers on mobile. Different market, different game design fit.
- Argentina, Colombia, Chile, Peru are all mobile-led with strong free-to-play penetration and growing console adoption.
The big localization decision in Spanish is which Spanish to ship. Three options:
- Castilian Spanish (Spain only). Defensible if Spain is your only target.
- Latin American Spanish. A regional standard that works across most of LATAM but reads as foreign in Spain.
- Neutral Spanish. A practical cross-market variant that works for UI, tutorials, and store copy. Less ideal for humor, slang, or strong character voice.
For most studios, the right answer is neutral Spanish for the base text, with regional adaptation only for dialogue-heavy or culturally specific content. Shipping two full Spanish variants (Castilian and LATAM) only makes sense at AAA scale.
Also worth noting: the United States has 45.5 million native Spanish speakers, projected to become the world’s second-largest Spanish-speaking country by 2060. A Spanish build is increasingly a North American asset, not just a Latin American one.
Read the full Spanish game localization breakdown for per-country market data, “voseo” and formality guidance, and storefront compliance notes.
What FIGS languages have in common, and what'll bite you
The four FIGS languages share enough localization gotchas that any team taking on the full bundle should plan for them once, centrally, rather than rediscovering each one per language.
All four expand from English, but at different rates. German is the worst (up to 35%), Spanish and French sit around 15–20%, Italian closer to 10–15%. If your UI was designed pixel-tight in English, it will break. Budget for UI rework, not just translation.
English uses “you” for everyone. The FIGS languages don’t.
- French: “tu” vs. “vous.”
- Italian: “tu” vs. “Lei.”
- German: “du” vs. “Sie.”
- Spanish: “tú” vs. “usted” (plus “vos” in voseo regions like Argentina).
This isn’t a translator’s call, it’s a creative direction call. Pick a register per game and document it before translation starts. Switching mid-script reads as broken.
Articles, adjectives, and many noun forms change with gender. This wrecks the reusability of strings that reference the player (“You have completed the quest”), avatars, and dynamic UI. Plan for context-aware strings and avatar-aware variants from the start.
Umlauts (ä, ö, ü), eszett (ß), cedillas, accents, tildes, inverted punctuation (¿, ¡). Test font rendering across all platforms early. Test input fields. Test chat systems if you have them.
All four markets (especially Germany, France, and Italy) have growing player expectations for full voice-over rather than subtitled-only releases. For premium console releases, subtitled-only is now perceived as a half-finished product. Budget accordingly or be deliberate about why you’re not.
Germany’s §86a StGB is the most famous, but every FIGS market has its own ratings system (PEGI EU-wide, plus national variants like USK in Germany and IFT in Mexico), microtransaction rules, and child-data requirements. The EU Consumer Protection Cooperation Network’s 2025 principles on in-game virtual currencies affect all four EU markets simultaneously.
How to prioritize FIGS for your game
f you can do all four FIGS languages from day one, congratulations, do that. The rest of you have to sequence.
Here’s our opinionated take. For most studios, the right order is: German, Spanish, French, Italian. The reasoning:
- German first because Germany has the highest revenue density (most $ per localized word) and the most mature player expectations. If you can satisfy German gamers, you can satisfy anyone.
- Spanish second because it doubles your addressable market in one move and unlocks LATAM growth.
- French third because France is solid revenue and the long-term African upside is real.
- Italian last because the market is smaller, but don’t skip it. The ARPU is too high.
But this order isn’t right for everyone. Three big caveats:
When FIGS isn't enough, and when it's too much
A few honest notes on where FIGS fits in the larger language strategy.
FIGS is too much when you’re a tiny indie launching a niche title with no European traction, you have under $10–15K for total localization, or your game is so culturally specific to one region that the FIGS markets won’t connect with it regardless.
FIGS isn’t enough when you’re targeting global scale. Once FIGS is shipped (or even before, depending on your title), there are two coherent paths forward. Which one is right for you depends on whether you’re optimizing for total revenue potential or for cost-and-risk efficiency.
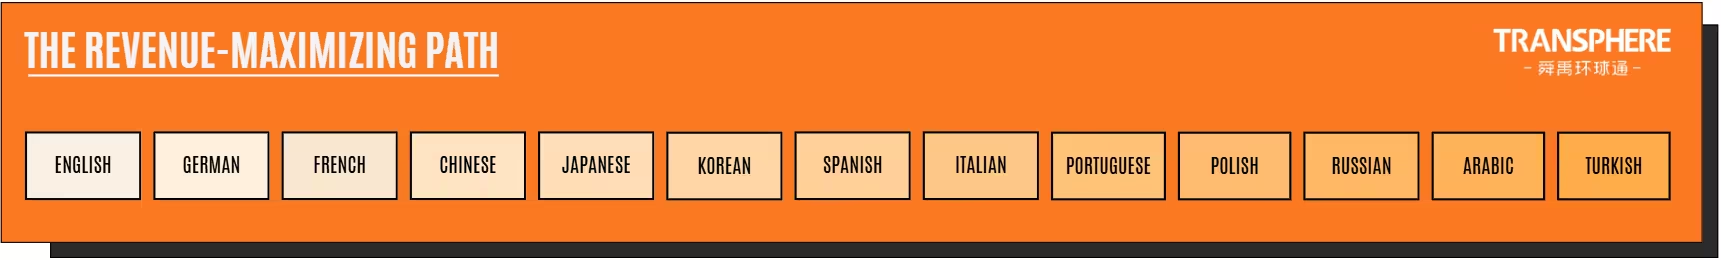
1. Maximizing revenue: Go straight to CJK
If you look at the data dispassionately, the biggest gaming markets after the US and UK aren’t in Europe, they’re in East Asia.
- China: Roughly $48.7 billion in gaming revenue (2024)
- Japan: Roughly $16.6 billion.
- South Korea: Roughly $7.1 billion.
- In total: $72 billion (that’s more than three times the combined FIGS markets).
While we may be biased, we often argue that E + CJK delivers more capturable revenue than EFIGS does, and that for studios with the budget and infrastructure to support it, CJK should come immediately after FIGS, or even before completing the FIGS bundle.
Caveat: The real costs of going CJK early
The revenue is real. The friction is also real. Be honest about what you're signing up for:
1. Per-word translation rates vary across CJK. Simplified Chinese is affordable, sometimes comparable to FIGS rates ($0.09–0.15/word) due to the large translator pool. Japanese and Korean are notably more expensive ($0.15–0.28/word) and the qualified game-translator pool is much smaller.
2. UI and font work is significant for all three. Glyph rendering, font licensing (Chinese fonts in particular are licensing-heavy), input methods, and text-wrapping behavior all need engineering work. You can't just swap strings.
3. Cultural adaptation > literal translation. CJK markets reward titles that feel localized rather than translated. Lazy CJK localization is even more visible than lazy German localization.
4. Platform and regulatory friction is real, especially for China. Publishing in China requires a local partner and an ISBN (game license), which is non-trivial. Japanese platforms (DMM, Yostar partnerships for mobile) and Korean Game Rating Board approval add their own steps.
If your studio doesn't have a producer who's done CJK before, plan to absorb that learning curve, or work with an agency that has.
2. Minimizing cost and drift
If you’re more cost-sensitive, more risk-averse, or simply not ready for the operational complexity of CJK, there’s an alternative path that bolts onto FIGS naturally.
Brazil is the largest gaming market in Latin America with 100 million gamers and $2.5–4 billion in annual revenue (depending on source), making it the world’s 10th-largest gaming market.
Pt-BR translation rates are similar to FIGS rates, the linguistic distance from Spanish is small (your Spanish translator can usually QA your Portuguese), and the cultural fit with Western games is high. For mobile especially, the case is overwhelming, Brazil is 60%+ mobile-first.
Poland has roughly 20 million gamers and a video games market reaching $2 billion in 2024–2025. More importantly, Polish gamers over-index dramatically on PC and Steam. If your title has a Steam presence, Polish localization punches well above its weight. Polish is also one of the cheaper professional localization languages ($0.10–0.18/word) and the gamer audience is genuinely passionate.
Both languages are linguistically and culturally adjacent enough to FIGS that your existing localization team can usually extend into them without major infrastructure changes.
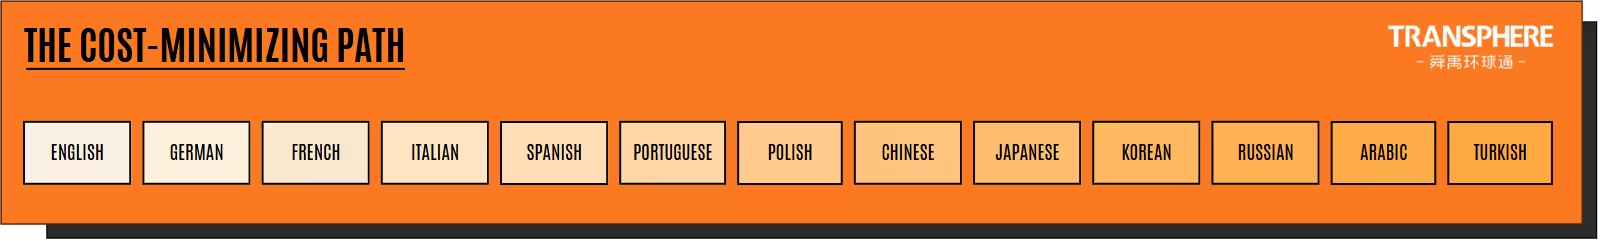
This path covers roughly 85% of the global addressable gaming market while keeping your localization spend predictable and your operational risk low. CJK still comes, just after you’ve built the localization infrastructure and accumulated enough revenue from the easier markets to fund it properly.
Which path is right for you?
Neither path is universally correct. The honest decision tree:
- Mid-to-large studio with budget, infrastructure, and platform partnerships in place should pick the first option (revenue maximization). Don’t leave $72B on the table to save on translation costs.
- Smaller studio, indie, or first international expansion should pick the second option. Build the muscle on adjacent markets before tackling CJK complexity.
- Mobile F2P title? A bit of a hybrid. Brazilian Portuguese and Simplified Chinese both belong near the top, because mobile markets in both regions are massive and conversion behavior is well-understood.
Whichever path you take, the principle is the same as with FIGS itself: don’t ship a language half-heartedly. A half-translated CJK release will damage your brand in those markets more than no release at all.
Key takeaways
- FIGS game localization remains the single highest-ROI localization investment for most studios releasing in English, despite competition from Chinese, Arabic, and Korean.
- The four FIGS languages reach a combined addressable audience approaching half a billion gamers and $15+ billion in annual game software and in-game revenue across core markets.
- Treat FIGS as four markets, not one. Germany monetizes best, Italy has the highest ARPU, French has the longest growth runway, Spanish has the broadest reach.
- For most studios, prioritize German → French → Spanish → Italian, but lead with Spanish for mobile F2P, and build German first if your content has historical/fascist themes.
- Budget for the shared challenges (text expansion, formality decisions, gendered grammar, voice-over expectations, and regulatory compliance) once, centrally, before language-specific work begins.
- A bad FIGS translation costs more than no translation. Either do it well or don’t do it.
Looking to scope FIGS localization for an upcoming release? Get in touch, we’d be glad to walk through the markets that fit your game best.